'Enraging': WA residents despair as insurance premiums climb again
Published in Business News
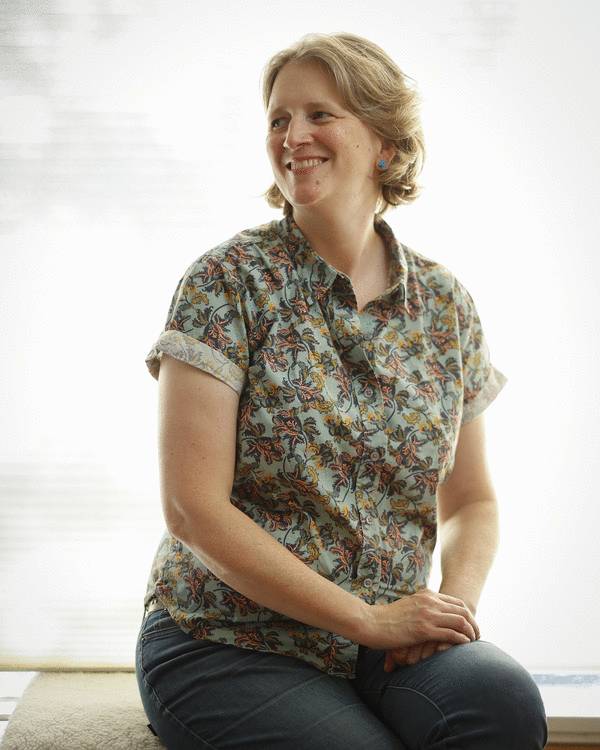
SEATTLE — Kate Neville is dreading the new year.
As a freelance grant writer, Neville has to buy her own health insurance, and for years her premiums have been climbing.
Her Kaiser Permanente plan cost around $350 per month just three years ago. Today, she pays $633 per month for the same plan — a nearly 80% increase. As open enrollment began Sunday, she’s bracing for another big jump: In 2027, Neville is looking at monthly premiums of nearly $800.
“It’s stressful,” Neville said in an interview last month. She wonders when she’ll hit her limit. At a certain point, you literally cannot pay for it.”
Neville is one of nearly 250,000 people in the state of Washington who buy their own insurance, typically because they don’t have access to coverage through an employer or public programs like Medicare and Medicaid. Some are self-employed, or they may have been laid off, or they stopped working before the age of 65.
For years, many of these individual buyers could rely on enhanced tax credits, introduced during the pandemic to help middle-class households afford premiums. Those tax credits expired last year despite a bruising government shutdown over preserving them. Since then, thousands in Washington have had to pay the full cost of premiums on their own for the first time in years, at a moment when the cost of insurance is rising rapidly.
For 2027, insurance carriers in Washington have projected that rates will increase by more than 22% on average, another blow to individual buyers’ budgets. It's a significantly higher jump than the national average of 13%.
Many are making sacrifices to keep their coverage. Some are weighing whether to shutter their small businesses altogether. Others are saving less for retirement or spending less on other necessities.
“People are making choices between seeking healthcare, staying insured, and other things that are critical to them living their lives,” said Laura Kate Zaichkin, director of market competition and affordability at the Washington Health Benefit Exchange. “Whether that's gas or groceries or paying their utility bill.”
‘So stunned’
Although insurance premiums typically trend upward, the projected increases in Washington next year are particularly staggering.
Not only is the average rate hike for 2027 the second-highest on record for the state, it also follows multiple consecutive years of double-digit jumps. Compared with other states, Washington’s rate increases are some of the highest.
After years of compounding, insurance premiums now rival most other costs of living for many people.
Numerous factors are driving next year’s rate hikes.
Before increasing rates, insurance carriers have to submit requests to the office of the insurance commissioner explaining why hikes are warranted. The state insurance commissioner is legally required to approve rate increases, as long as they are mathematically justified.
In this year’s requests, insurance carriers underscored the rising cost of healthcare itself, citing inflation, higher drug prices and increasingly expensive medical technology, among other factors. When insurers pay more in claims, that eventually translates to higher premiums.
Those can be painful for people to absorb.
Davina Kotulski, 56, buys her own insurance because she’s self-employed.
For years, her premiums were manageable, especially when the enhanced tax credits were put in place in 2021.
Then Kotulski was hit by an enormous price increase. In 2025, she paid around $600 per month in premiums for a gold plan; now she pays $1,000. The increase represents higher premiums and the loss of the tax credits.
That’s not the end of it.
In October, Kotulski got married. Her wife was previously on Medicaid, known as Apple Health in Washington, the public insurance program for people with low incomes, which she won’t qualify for after the marriage. As Kotulski adds her wife to her plan, her monthly premium will be around $1,600 through the rest of this year, she estimates.
Next year, the couple is looking at monthly premiums around $2,120. If they add Kotulski’s stepson to the plan, the family’s combined premium will be over $2,530.
“I'm having a very hard time wrapping my brain around this,” she said. “It’s enraging. Where’s that money supposed to come from?”
Reluctantly, Kotulski will have to set aside less money for retirement and for her stepson’s college savings. She can’t believe she’s spending so much just to maintain coverage.
“You’re asking people and families to trade the discretionary income they may have had to improve their quality of life to now pay insurance companies for a peace of mind,” said Tina Wang, an insurance broker who works with clients who buy their own coverage.
Over the past year, Wang has noticed her clients' shock when she tells them about premium increases.
“They're so stunned by these numbers that they're speechless,” she said. “They're frozen. They don't know what to do.”
Spiraling costs in WA
Many are opting out of insurance altogether.
This year, 36,500 fewer people in Washington enrolled in an individual insurance plan — a drop of almost 13%, according to data from the state exchange.
Ambrose Bittner, 64, is one of those people.
The self-employed owner of a travel company, Bittner made the difficult decision to go uninsured about a year ago, when the premium tax credits expired. By doing so, he calculated that he could save $850 per month in premiums and put the money toward retirement instead.
“I feel very good,” he said recently, reflecting on his choice one year later.
He’s incurred just a few medical costs out of pocket, including cholesterol medication that runs about $20 every three months and a $99 heart scan. Before the end of the year, he’s going to Bangkok, where he plans to get a broken tooth fixed and a skin cancer screening.
He just needs to wait a few more months before he turns 65 and becomes eligible for Medicare coverage.
The decision is a risky one. In the case of a health emergency, uninsured people could find themselves saddled with enormous medical bills.
There are also broader ramifications. When people drop coverage, rates for people who remain insured go up.
That’s because younger and healthier people tend to be the first to opt out when premiums rise, leaving behind a pool of enrollees that’s sicker and requires more expensive care. Higher claims then force insurers to raise their rates, which can then prompt even more people to drop coverage.
That trend is likely to continue, said Wang, the insurance broker. “Unfortunately, we will see many more uninsured in 2027.”
As premiums rise, coverage worsens
Some people who stay insured are considering cheaper coverage.
David Powell, 64, pays $1,358 per month for a UnitedHealthcare bronze-level plan. He started buying his own insurance in 2024 after a layoff led him to retire early.
At the start of 2026, his premium increased 20%. Now, he’s looking at a new jump of around 24%, or a total of $1,685, at the start of 2027 if he sticks with his current plan.
“It's painful but we can afford it,” he said last week, while browsing his options on the exchange website.
To save, he’s considering switching to a bare-bones plan. But even that option comes at a higher price compared with his current premiums, an increase of around 12%. Under such a plan, Powell would also face significantly higher out-of-pocket costs in case of an emergency like a car crash or a heart attack.
“That's the gamble,” he said. On the eve of open enrollment, he decided to stick with his pricier plan just to be safe.
To free up cash, he plans to stop putting money into his health savings account.
Powell still considers himself among the “lucky ones,” because he can still take steps to afford insurance until he is eligible for Medicare. He’s more worried for people who still have many more years to go.
People like Neville, the freelance grant writer, who doesn’t know where she’ll scrounge together the money to pay for next year’s higher premiums.
"Some of it might come from reduced retirement contributions,” she said. “Some of it might come from reduced vacation. Some of it might come from higher rates to clients."
That last option puts her in a bind. Most of Neville’s clients are nonprofits. Raising her rates would mean losing some of them. As her expenses rise and her income falls, she finds herself wondering if her business is even sustainable. Occasionally, she considers whether she should just go back to work for an employer. The possibility feels more inevitable every day.
"I just wonder how much more vibrant the economy would be if healthcare wasn't so astronomically expensive to pay for out of pocket," she said. It prevents a lot of people from being entrepreneurs.”
©2026 The Seattle Times. Visit seattletimes.com. Distributed by Tribune Content Agency, LLC.
Comments